
Most 401(k) fees do not arrive as an obvious bill. They may be deducted from investment returns, taken from the account as periodic charges, or built into services you barely notice, which can make an apparently inexpensive retirement plan cost more than expected.
That matters because fees compound in reverse. A small annual drag can remove years of potential growth, especially when your account balance is largest near retirement.
The good news is that many fees must be disclosed, and some can be reduced once you know exactly where to look.
“Hidden” Does Not Always Mean Secret
Federal rules require participant-directed 401(k) plans to provide information about plan and investment fees.
Investment information is generally provided before participants first direct their investments and then periodically, while administrative and individual charges deducted from an account should also appear in plan disclosures or statements.
The bigger problem is visibility. Investment expenses are often removed inside a fund before the return appears in your account, while other charges may appear under unfamiliar names that are easy to overlook.
Government research has also found that many retirement-plan participants do not fully understand the fees they pay. That matters because simply receiving a disclosure does not guarantee that someone knows how much a charge costs in real dollars.
The Department of Labor has illustrated how powerful the difference can become. In one long-term example using a $25,000 starting balance, a 7% average annual return and no additional contributions, a one-percentage-point difference in annual fees reduced the ending balance by roughly 28% over 35 years.
Before looking at the 16 possible charges, it helps to understand current fee levels. Many 401(k) investors now hold mutual funds with considerably lower expense ratios than retirement savers paid decades ago.
| Fee Fact | Recent Figure | Why It Matters |
|---|---|---|
| Average expense ratio paid by 401(k) equity mutual-fund investors | 0.27% in 2025 | Gives a broad comparison point |
| Average 401(k) hybrid mutual-fund expense ratio | 0.40% in 2025 | Costs vary significantly by investment type |
| Average 401(k) bond mutual-fund expense ratio | 0.19% in 2025 | Some investments have particularly low ongoing costs |
| Equity mutual-fund assets below a 0.50% expense ratio | 76% at year-end 2025 | Much of today’s 401(k) money is in lower-cost funds |
| 401(k) mutual-fund assets held in no-load shares | 97% at year-end 2025 | Traditional sales loads are increasingly uncommon |
1. Fund Expense Ratios
An expense ratio is the ongoing cost of operating an investment fund. It is normally expressed as a percentage of the money invested and deducted within the fund itself, meaning the investment return you see has generally already been reduced by that expense.
This is often one of the easiest recurring 401(k) costs to influence. If your plan offers multiple funds serving a similar purpose, compare their expense ratios along with their investment strategy, risk, diversification, and performance history.
A fund costing 0.10% annually and another costing 0.80% may appear similar at first glance, but the difference becomes substantial over decades. That does not automatically make the cheaper fund better, although cost deserves serious attention when two investments otherwise perform similar jobs.
2. 12b-1 Distribution and Service Fees
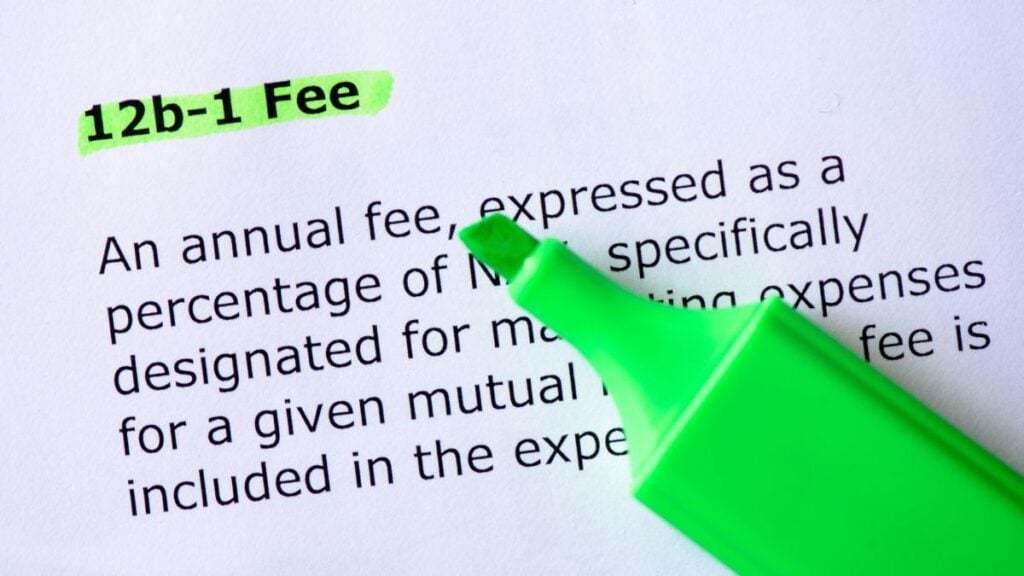
Some mutual funds charge 12b-1 fees for distribution, marketing, or shareholder-related services. These charges are paid from fund assets, meaning shareholders indirectly bear the expense.
The important point is that a 12b-1 charge is typically included inside the fund’s overall expense ratio. Do not automatically add it to the expense ratio again or you could double-count the same cost.
If one fund contains a meaningful 12b-1 charge while a comparable option does not, it may be worth investigating the alternatives available in your plan. Your participant disclosure or fund prospectus should provide the necessary information.
3. Sales Loads
A sales load is essentially a commission connected with buying or selling certain mutual-fund shares. Front-end loads are generally paid when an investment is purchased, while deferred loads may apply when shares are sold.
Fortunately, these charges are considerably less common inside modern 401(k) plans. Recent industry data show that the overwhelming majority of 401(k) mutual-fund assets are now held in no-load share classes.
Do not assume a sales charge applies merely because it appears in a fund’s general prospectus. Some fees may be waived for retirement-plan investors, so verify what your specific plan actually charges.
4. Revenue-Sharing Arrangements
Revenue sharing can occur when an investment provider pays part of its revenue to a recordkeeper or another service provider. The arrangement may help cover administrative costs associated with operating the retirement plan.
This can make fees difficult to understand because the cost may already be reflected inside the investment’s expense ratio. It is therefore important not to count revenue sharing as a completely separate percentage without examining how your plan structures the arrangement.
An employee usually cannot renegotiate revenue sharing individually. You can, however, ask whether your plan uses it, whether any excess amounts are credited back to participants, and whether lower-cost institutional share classes are available.
5. Managed-Account or Personalized Advice Fees
Some 401(k) plans offer managed-account services that select investments, rebalance your portfolio, or provide personalized recommendations. These services may charge an additional percentage of your balance.
A fee of 0.30%, 0.50%, or more can look small until it is applied to a large retirement balance every year. Someone with $600,000 paying an additional 0.50% would be paying about $3,000 annually before considering the underlying fund expenses.
That does not automatically make the service a poor deal. Someone who uses and values personalized management may decide the cost is worthwhile, but you should know whether you are enrolled and what you are actually receiving in return.
What One Percentage Point Can Do Near Retirement
Percentages such as 0.25%, 0.75%, or 1.00% can seem insignificant when viewed on a disclosure. The effect becomes easier to understand once those percentages are translated into decades of lost compounding.
Consider a hypothetical person with $500,000 earning 6% annually before fees for 20 years, with no additional contributions or withdrawals. These numbers are illustrations rather than predictions because actual investment returns will vary.
| Annual Fee Drag | Approximate Balance After 20 Years |
|---|---|
| 0.25% | $1,529,599 |
| 0.50% | $1,458,879 |
| 1.00% | $1,326,649 |
| 1.25% | $1,264,884 |
The difference between a 0.25% and 1.25% annual drag is roughly $264,700 under these assumptions. Part of that difference comes directly from fees, while another part comes from the investment growth those deducted dollars never had the opportunity to earn.
That is why fees deserve more attention as retirement approaches. A percentage that seemed trivial on a $30,000 account becomes far more expensive after decades of saving have pushed the balance into the hundreds of thousands of dollars.
6. General Plan Administration Fees
A 401(k) does not run itself. Plans require administration, participant communications, regulatory filings, compliance work, customer support, and numerous other services.
Depending on how the employer structures the plan, the company may pay these expenses, participants may pay them, or the costs may be divided between both. They may appear as flat charges, asset-based percentages, or expenses indirectly paid through investments.
Employees usually cannot simply opt out of these fees while remaining in the plan. What you can do is understand how the costs are calculated and ask whether your employer periodically reviews competing service providers and plan expenses.
7. Recordkeeping Fees
Recordkeepers track contributions, balances, investment elections, beneficiaries, distributions, statements, loans, and other information associated with your account. That work costs money, and different plans pay for it in different ways.
Some plans charge participants a flat dollar amount, perhaps every quarter or every year. Others calculate recordkeeping charges as a percentage of assets or fund part of the service through investment-related compensation.
This is why looking only at your mutual funds can provide an incomplete picture. A plan may offer extremely cheap investments while separately charging for recordkeeping, while another plan may bundle more of that cost into the funds themselves.
8. Trustee or Custody Expenses
401(k) assets must be properly held, safeguarded, and administered. Trustee and custody services are part of the infrastructure required to operate retirement plans.
These charges are usually not expenses an individual worker can switch off. Depending on the plan, they may be paid by the employer, charged against plan assets, or incorporated into a broader administrative arrangement.
Your goal is not necessarily to eliminate this type of fee. It is to understand whether participants pay it and whether the total cost of running the plan appears reasonable for the services provided.
9. Legal, Accounting, Audit and Compliance Costs
Retirement plans operate under numerous federal rules, which creates expenses for legal services, accounting, testing, reporting, compliance work, and sometimes independent audits. These services help keep the plan functioning properly.
Some employers absorb those expenses, while others allow certain reasonable plan expenses to be paid from plan assets. An administrative fee therefore does not automatically mean the plan is poorly managed.
The more useful question is whether the overall cost is reasonable. Employers and other plan fiduciaries are expected to pay attention to plan expenses rather than simply choosing a provider and ignoring costs indefinitely.
10. Flat Account-Maintenance Fees
Some 401(k)s charge a flat amount each quarter or year simply for maintaining the participant’s account. The dollar amount may seem small, particularly when the account balance is large.
Suppose a plan charges $15 each quarter. That equals $60 a year, which represents only 0.01% of a $600,000 account but 0.60% of a $10,000 account before considering any other expenses.
Flat charges therefore deserve extra attention when you have small balances sitting in former employers’ retirement plans. Compare the old plan with the alternatives legally available to you before deciding whether moving the money makes sense.
11. Brokerage-Window Access Fees
Some employers allow participants to open a self-directed brokerage window inside the 401(k). This gives investors access to investments beyond the plan’s standard menu.
Greater choice can be useful, but the feature may carry additional maintenance or access fees. Those costs may be charged annually, quarterly, or according to the particular services used.
Do not assume more investment choices automatically produce better results. If your regular plan menu already provides diversified, reasonably priced investments that meet your needs, paying extra for a brokerage window may add complexity without much benefit.
12. Brokerage Commissions and Transaction Charges
Once you enter a brokerage window, additional expenses may appear. Depending on the provider, these can include commissions, transaction fees, mutual-fund purchase charges, or other trading-related expenses.
Frequent trading can make seemingly small charges accumulate faster than expected. Someone making dozens of unnecessary transactions may create an expense that a patient long-term investor never incurs.
Before making a trade, check exactly what the transaction will cost. If the investment objective can be achieved with a lower-cost option already available in the regular 401(k), the brokerage window may not be necessary.
Which Fees Can You Actually Get Rid Of?
The phrase “get rid of your 401(k) fees” sounds attractive, but completely eliminating every cost is rarely realistic. Some expenses pay for necessary services, while others are optional charges participants can avoid.
The practical goal should be eliminating unnecessary fees and lowering excessive ones without damaging your investment strategy. That requires separating costs you control from costs controlled by the employer.
| Fee Area | Can You Change It Personally? | Practical Response |
|---|---|---|
| Fund expense ratio | Often | Compare similar investments |
| Managed-account fee | Often | Determine whether the service is worth paying for |
| Brokerage window | Usually | Avoid it if regular plan choices are adequate |
| Trading charges | Usually | Reduce unnecessary transactions |
| New loan fees | Before borrowing | Check all costs first |
| Plan administration | Usually not | Raise concerns with employer or plan committee |
| Recordkeeping | Usually not | Ask how costs are calculated |
| QDRO processing | Often unavoidable | Follow plan procedures carefully |
| Contract or surrender fees | Depends | Review contract terms before moving money |
The existence of a fee does not automatically make it bad. A reasonably priced service that genuinely helps participants is very different from an optional charge that provides little value.
13. 401(k) Loan Origination and Maintenance Fees
If your plan permits 401(k) loans, borrowing from the account may involve more than simply paying interest. Plans can charge origination or setup fees and sometimes ongoing maintenance charges.
A participant might pay a fixed amount simply to create the loan. That charge can make a small loan considerably more expensive on a percentage basis than a larger one.
Before borrowing, examine the complete loan schedule rather than focusing only on the interest rate. Also consider repayment requirements and the potential investment growth lost while money is removed from the market.
14. Withdrawal and Distribution Processing Fees
Retirement plans may charge fees when participants request certain withdrawals or distributions. Charges can depend on whether you request installments, a lump sum, hardship withdrawal, paper check, or another form of payment.
Someone nearing retirement should understand these costs before designing a withdrawal schedule. Taking frequent distributions could potentially generate more charges than choosing a different payment arrangement, depending on the plan.
Ask what each available withdrawal method costs. A five-minute review before retirement can prevent years of unnecessary transaction expenses.
15. QDRO Processing Fees
A Qualified Domestic Relations Order, commonly called a QDRO, may be needed when retirement assets are divided following divorce or used for certain family-support obligations. Processing these orders can involve administrative and legal work.
A defined-contribution plan may assess reasonable expenses associated with reviewing and processing a QDRO. Depending on the plan, those charges may be allocated to the account affected by the order.
This type of expense is usually not something a participant can simply avoid when a QDRO is legally necessary. Asking whether the plan provides model documents or pre-approval procedures may help reduce errors, revisions, and unnecessary processing.
16. Insurance, Surrender and Contract Charges
Some retirement plans contain insurance products, annuity features, or other contracts with additional expenses. Potential costs can include mortality and expense charges, administrative expenses, surrender fees, or termination charges.
These fees matter most before you make a change. Moving money without understanding the contract could potentially trigger a charge that would not have applied if you had waited or used another option.
At the same time, some insurance or annuity products provide guarantees or features that ordinary mutual funds do not. Evaluate both the cost and the benefit rather than assuming that any investment carrying a higher fee is automatically inferior.
How to Audit Your 401(k) Fees in About 20 Minutes
You do not need to become a retirement-plan expert to find the most important costs. Start with your annual participant fee disclosure, recent account statement, current investments, and information about any optional services you use.
The goal is to identify the expenses actually affecting your account rather than studying every fee your plan could theoretically charge. A focused review can often reveal the biggest opportunities very quickly.
| Time | What to Check | What You Are Looking For |
|---|---|---|
| Minutes 1–5 | Annual participant fee disclosure | Expense ratios and plan-level fees |
| Minutes 6–9 | Latest account statement | Dollar charges deducted from the account |
| Minutes 10–13 | Investments you currently own | Expense ratios and share classes |
| Minutes 14–16 | Optional services | Advice, brokerage windows and loans |
| Minutes 17–18 | Former-employer 401(k)s | Maintenance and distribution charges |
| Minutes 19–20 | Questions for administrator | Fees you cannot identify or control |
Do not automatically switch to the cheapest investment you find. Two funds with different expense ratios may have completely different investment objectives, risk levels, holdings, or diversification.
Instead, compare funds that serve the same role in your portfolio. If two options provide similar exposure and one costs substantially less, that is where the fee difference becomes especially worth examining.
