Retirement money rarely disappears because of one dramatic mistake. More often, it leaks away through choices that feel reasonable in the moment: one nicer car, one extra trip, one more loan to an adult child, or one “safe” investment promising a little more income.
The danger is that many of these choices do not stay one-time expenses. They raise monthly spending, trigger taxes, increase portfolio withdrawals, or reduce flexibility just when retirement money needs room to absorb market drops, healthcare costs, and surprises.
Note: This article provides general educational information, not individualized financial, tax, investment, legal, Medicare, or Social Security advice.
1. The Retirement Reward Spending Spree
After decades of saving, the first months of retirement can create a powerful feeling: We finally made it, so now we can spend.
There is nothing wrong with celebrating. The trouble begins when the celebration quietly becomes the new normal through upgraded restaurants, frequent trips, expensive hobbies, premium services, and purchases that were postponed during working years.
Early retirement is also a sensitive time for portfolio withdrawals. Morningstar’s recent research notes that losses early in retirement can be especially damaging when a retiree is simultaneously withdrawing money, because fewer assets remain available to participate in a later recovery.
A useful approach is to create a separate first-year celebration budget. Spend it deliberately, enjoy it fully, and keep it separate from the recurring amount your retirement plan must support year after year.
2. Letting a Good Market Year Raise Your Lifestyle
A rising investment account can create the impression that retirement has suddenly become more affordable. The temptation is to upgrade travel, replace the car, increase gifts, renovate the house, and treat the higher balance as permanent wealth.
Markets do not move upward in a straight line, though. If spending rises after a strong year and remains high after markets fall, withdrawals can become much more painful.
This is one reason flexible spending can help retirees manage sequence risk. Fidelity and Morningstar both discuss the value of adapting discretionary withdrawals when market conditions or portfolio values deteriorate.
Enjoying part of a strong year may be perfectly reasonable. Turning a temporary portfolio gain into a permanently higher cost of living deserves much more caution.
3. Buying the Retirement Toy Before Testing It
The RV, boat, sports car, golf-club membership, or workshop full of new equipment often represents something bigger than the object itself. It represents the retirement you pictured while you were still going to work every morning.
The problem is that ownership carries costs beyond the purchase price. Insurance, storage, maintenance, repairs, fuel, fees, and depreciation may continue even after your enthusiasm fades.
AARP has identified boats, RVs, timeshares, and other large lifestyle purchases among items that can leave some retirees with buyer’s remorse.
Renting first can be a powerful retirement tool. A two-week RV rental or several boat charters may answer a $50,000 question for a fraction of the price.
Before any major purchase, separate the sticker price from the lifestyle it creates. The second number often matters more.
| Question | One-time cost | Ongoing lifestyle cost |
|---|---|---|
| RV | Purchase price | Storage, insurance, fuel, repairs, campground fees |
| Second home | Down payment | Taxes, insurance, utilities, repairs, travel |
| Luxury vehicle | Purchase price | Insurance, registration, maintenance, depreciation |
| Club membership | Initiation fee | Monthly dues, dining minimums, activity fees |
| Major remodel | Construction bill | Higher insurance, maintenance and possible financing |
A purchase may still be worth making after this exercise. The goal is simply to judge the whole commitment instead of the exciting first payment.
4. Turning Every Travel Dream Into a First-Year Plan
Many retirees have a backlog of places they spent 30 years hoping to visit. Once work ends, it is tempting to schedule all of them immediately because time finally feels available.
The financial problem is concentration. Five expensive trips in 18 months can create much larger portfolio withdrawals than the same experiences spread over several years.
Travel also has a habit of expanding. Better hotel rooms, premium airline seats, restaurant meals, cruises, tours, insurance, pet care, and family trips can turn the original budget into something very different.
A better question is not, “Can we afford this trip?” Ask, “How many trips like this can our annual discretionary budget support without borrowing or taking unusually large investment withdrawals?”
Retirement should include experiences you worked hard to enjoy. Spacing them can help make sure there is still money and enthusiasm left for year ten.
5. Becoming the Permanent Bank of Mom and Dad
Helping an adult child with a genuine emergency can be deeply important. The financial danger begins when occasional assistance becomes permanent rent support, car payments, tuition, credit-card rescues, phone bills, or monthly transfers.
AARP and Fidelity both emphasize checking the parents’ own retirement needs before committing to ongoing support for adult children.
Parents also face something younger family members may not: lost money is difficult to replace after paychecks stop. A 35-year-old can often rebuild savings over decades, while a 70-year-old may have fewer options.
Generosity therefore needs a ceiling, not guilt. Decide what amount your retirement can safely give and make the boundary clear before a temporary rescue becomes expected income.
The following test can help families separate manageable help from a commitment that deserves a deeper review.
| Family request | Lower-risk approach | Warning sign |
|---|---|---|
| Emergency repair | Defined one-time gift | Repeated emergencies every few months |
| Temporary housing help | Set amount and end date | Open-ended monthly transfers |
| Education help | Preplanned education budget | Retirement withdrawals made without a limit |
| Grandchild expense | Gift within established family budget | Gifting that requires debt or selling investments unexpectedly |
| Business idea | Money you could afford to lose | Your retirement security depends on repayment |
Family support is not automatically a mistake. The risk comes when love prevents everyone from discussing limits.
6. Giving Grandchildren More Than the Plan Can Support
Grandchildren create their own financial temptation. Birthdays become larger, college help grows, weddings appear, family vacations expand, and grandparents may want to give money now rather than leave it later.
That can be meaningful when it fits comfortably within the retirement plan. It becomes more concerning when gifts are financed with large withdrawals or when a retiree quietly reduces their own emergency reserve to avoid disappointing family.
There is also a psychological trap here. Once a large level of support becomes normal, reducing it later can feel like taking something away.
Create a family-giving budget just as you would create a travel budget. A fixed annual amount lets you be generous while protecting the retirement that makes future generosity possible.
7. Co-signing Because Saying No Feels Uncomfortable
Co-signing does not feel like spending money because no check leaves your bank account that day. That is precisely why it can be so tempting.
Yet a co-signer accepts a real obligation if the primary borrower cannot pay. That obligation can appear at the worst possible time, including after a job loss, divorce, illness, or business failure in the family.
The emotional question is usually, “Do I trust this person?” The retirement question is different: “Could I comfortably take over this entire payment without damaging my own plan?”
If the answer is no, the risk is larger than it first appears. You can still help someone explore a cheaper car, smaller loan, temporary housing arrangement, or direct gift that has a clear maximum.
8. Remodeling the House Before Testing Retirement Cash Flow
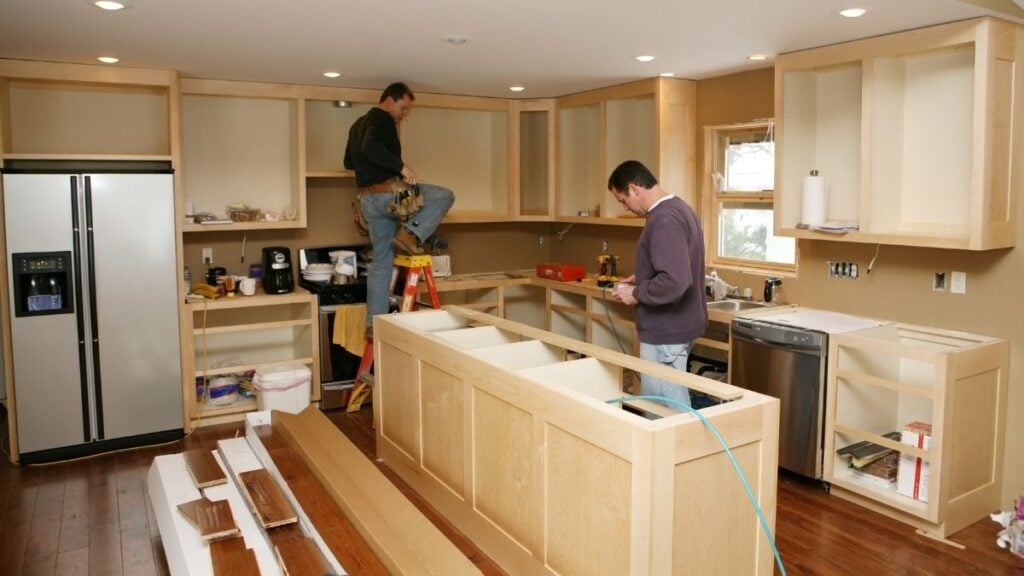
Retirement often creates a sudden desire to fix everything about the house. The kitchen looks dated, the bathroom needs work, the patio could be better, and now there is finally time to manage the project.
Some renovations can be sensible, especially repairs or changes that make a home easier to use over time. The temptation is turning a practical project into an unlimited “forever home” makeover.
Large remodels can require cash that would otherwise remain invested. Financing can be equally problematic because it adds another fixed monthly payment to retirement.
Before beginning, separate safety and maintenance from cosmetics. Then price each phase independently rather than committing to an entire transformation because contractors are already in the house.
9. Replacing a Paid-Off Vehicle Too Soon
A paid-off car can look less attractive the moment retirement begins. Suddenly, the comfortable SUV with newer technology, quieter seats, or better features feels like part of the retirement upgrade.
The monthly payment is often what makes the purchase seem manageable. But retirement planning works better when you look at the total cost, including purchase price, financing, insurance, registration, maintenance, and depreciation.
Transportation already represents a major household expense. In the latest BLS annual consumer expenditure report, housing and transportation together represented about half of average U.S. household spending in 2024.
Keeping a reliable paid-off vehicle another two or three years can preserve a surprising amount of flexibility. That does not mean keeping an unsafe or unreliable car simply to save money.
10. Letting Subscriptions and Convenience Spending Multiply
The dangerous retirement purchase is not always a $60,000 SUV. Sometimes it is $12.99, $18.99, $29.95, and $49.99 leaving the account month after month.
Streaming services, cloud storage, meal delivery, memberships, premium apps, home services, shopping subscriptions, restaurant delivery, and automatic renewals are easy to ignore because no individual charge feels important.
The math becomes clearer when you annualize everything. Ten unnecessary charges averaging $25 each equal $250 a month, or $3,000 a year.
AARP’s recent retirement-spending coverage specifically points to memberships, unused subscriptions, and other expenses that may no longer fit the retiree’s lifestyle.
Audit recurring charges twice a year. Canceling things you no longer value is very different from depriving yourself of things you genuinely enjoy.
11. Financing Wants Because the Monthly Payment Looks Manageable
Financing turns a large price into a small-looking number. That can make furniture, appliances, cars, renovations, electronics, and travel feel much more affordable than they really are.
Retirement is especially sensitive to fixed payments because income may not rise as easily as it did during working years. Every required payment reduces the amount of spending that can be adjusted after a market decline or unexpected medical bill.
The phrase “only $299 a month” deserves translation. Multiply it by the number of payments, add interest and fees, and compare that full amount with your discretionary retirement budget.
Debt is not automatically inappropriate in retirement. The key question is whether it improves the plan or simply allows today’s purchase to compete with tomorrow’s flexibility.
12. Taking a Large IRA Withdrawal Without Checking the Consequences
A traditional IRA can feel like a bank account after retirement. You need $40,000 for a renovation, so you withdraw $40,000 and assume the financial decision ends there.
It may not. Traditional IRA and many workplace-plan distributions are generally taxable, and larger income can affect more than the immediate purchase.
Medicare also uses income-related premiums for higher-income beneficiaries. In 2026, the standard Part B premium is $202.90 a month, while higher-income beneficiaries can pay substantially more depending on applicable income thresholds.
Required minimum distributions add another planning consideration. Under current rules, traditional IRA owners generally begin RMDs at age 73, while Roth IRAs owned by the original owner are not subject to lifetime RMDs.
This means the account you use to pay for a major purchase can matter almost as much as the price itself.
Before a large retirement-account withdrawal, pause long enough to answer four questions. The answers can expose costs that are invisible when you look only at the purchase.
| Decision | Question to ask | Why it matters |
|---|---|---|
| Large IRA withdrawal | What will this add to taxable income? | The withdrawal may cost more than its face value |
| Roth withdrawal | Is the distribution qualified? | Tax treatment depends on applicable rules |
| Social Security claim | Am I claiming for income needs or mainly discretionary spending? | Claiming age can permanently affect the monthly benefit |
| Big portfolio sale | Is the market currently down sharply? | Large withdrawals during losses can worsen sequence risk |
A retirement plan should not make normal spending impossible. It should help you choose the least damaging source of money when several sources are available.
13. Claiming Social Security Early Mainly to Fund Extras
Social Security can begin as early as age 62. For someone born in 1960 or later, full retirement age is 67, and starting at 62 can reduce the monthly retirement benefit by as much as 30% compared with waiting until full retirement age.
Waiting beyond full retirement age can increase the monthly benefit until age 70. For someone born in 1960 or later, SSA’s example shows age 70 producing 124% of the full-retirement-age amount.
None of that means everyone should delay. Health, employment, cash needs, marital considerations, longevity expectations, and other resources can make earlier claiming reasonable.
The temptation to watch is claiming primarily because you want additional spending money for travel, home upgrades, or another discretionary purchase without first comparing the lifetime tradeoffs.
14. Chasing High Income or “Safe” Investment Returns
Retirees naturally like investments that produce income. That makes offers promising high yields, steady monthly checks, or unusually safe returns especially attractive.
Unfortunately, the same desire makes retirees appealing targets for fraud. The FTC reported that adults age 60 and older reported $2.4 billion in fraud losses for 2024, up from about $600 million in 2020, with investment scams driving a large portion of reported losses.
Investor.gov warns specifically about guaranteed high returns, high-pressure tactics, unlicensed sellers, unusual transfers, and investments the investor does not fully understand.
A newer 2026 SEC alert also warns that scammers may misuse regulatory filings to create the appearance of legitimacy.
If someone says an investment is both unusually profitable and unusually safe, slowing down is a financial skill. Verify the person, the firm, the investment, the fees, and exactly how you can get your money back.
15. Making Investment Changes Because Markets Feel Frightening
The opposite temptation is just as powerful. Instead of chasing returns, some retirees want to move everything to cash after markets fall because watching account values decline feels unbearable.
Holding an appropriate cash reserve can be useful. Making a permanent portfolio change during a period of fear is a different decision.
Selling after losses can lock those losses in and change the long-term growth potential of the retirement portfolio. Meanwhile, keeping far more cash than the plan requires can expose spending power to inflation over a long retirement.
The right mix depends on personal circumstances, risk tolerance, income sources, time horizon, and withdrawal needs. The better habit is to decide your investment rules when markets are calm instead of inventing a new strategy during each frightening headline.
16. Ignoring Small Investment Fees Because the Percentage Looks Harmless
A fee of 0.25%, 0.75%, or 1% does not look like much when it appears on a statement. Over many years and a large retirement balance, however, the dollars removed from the portfolio can become meaningful.
The SEC explains that investment fees reduce both the money you keep and the amount remaining in your portfolio to earn future returns. Its 2025 investor bulletin illustrates how different fee levels can materially change the ending value of a hypothetical $100,000 investment over 20 years.
This does not mean every higher-cost service is automatically bad. Advice, planning, tax work, insurance features, or specialized management may provide value.
The temptation is paying without knowing what you are paying. Ask for the expense ratio, advisory fee, plan fee, transaction costs, insurance charges, and any surrender or exit costs in actual dollars whenever possible.
A Five-Minute Test Before Saying Yes
The goal of retirement planning is not to make every purchase feel dangerous. It is to protect the freedom to spend on the things that matter while reducing expenses that quietly take control of future decisions.
Before committing meaningful money, run through this short review. A delay of even 48 hours can separate a deliberate decision from an emotional one.
| Priority | What to review | Practical next step |
|---|---|---|
| 1. Total cost | Purchase price plus future costs | Calculate the annual cost, not just monthly payment |
| 2. Funding source | Cash, taxable account, IRA, Roth or debt | Check tax and withdrawal consequences first |
| 3. Repeatability | One-time expense or new lifestyle standard | Ask whether you can afford it again next year |
| 4. Flexibility | Can the expense be reduced later? | Be cautious with long contracts and fixed payments |
| 5. Alternatives | Rent, delay, buy used, travel off-season, smaller gift | Compare at least one lower-cost version |
| 6. Family effect | Does someone else now expect continued support? | Establish amount and end date before paying |
This review will sometimes tell you to spend the money. That is a successful outcome when the decision fits the plan and the purchase is genuinely worth it to you.