
A retirement decision can take years to prepare, yet one signature can change your financial future in minutes.
A document that looks like routine paperwork may reduce a spouse’s income, trigger an unexpected tax bill, or give someone control over your savings. The problem is that these consequences are not always explained clearly when the papers arrive.
Many people focus on how much money they have saved while overlooking the agreements that determine what happens to that money.
Why Retirement Paperwork Deserves More Attention Than Most People Give It
Retirement paperwork is not simply about confirming your last day at work or choosing where your pension check should go. Some forms determine how your savings are taxed, what your family receives after your death, and who can make financial decisions on your behalf.
The biggest danger is not necessarily dishonest paperwork. It is signing a legitimate agreement without understanding what you are giving up, what happens later, or whether a better option exists.
| Document | What Could Go Wrong | What to Check First |
|---|---|---|
| Retirement or severance agreement | Giving up certain legal claims or benefits | Waivers, payments, deadlines |
| Pension election form | Reducing or eliminating survivor income | Survivor benefits and payout options |
| 401(k) or IRA rollover form | Triggering taxes or withholding | Account destination and transfer method |
| Annuity contract | Locking money into costly withdrawal terms | Fees, guarantees, surrender charges |
| Beneficiary designation | Leaving assets to the wrong person | Primary and backup beneficiaries |
| Financial power of attorney | Giving someone more control than intended | Authority, timing, and safeguards |
Not everyone will encounter all six documents. However, understanding the ones that apply to your circumstances can prevent problems that become much harder to correct after retirement begins.
1. The Retirement or Severance Agreement That May Take Away More Than You Realize
A retirement or severance agreement can look especially attractive when an employer offers extra money for leaving. A lump-sum payment, extended insurance coverage, or additional retirement benefits may make signing seem like an easy decision.
However, the agreement may also contain a release of certain legal claims against the employer. It may include confidentiality provisions, restrictions on sharing company information, or conditions affecting future employment.
The most important question is not just what you receive. It is what you agree to give up in exchange.
For example, an employee who signs a valid release of certain employment claims may lose the ability to recover compensation through a later lawsuit based on those claims. That can matter if the employee later discovers a workplace dispute was more serious than originally understood.
Workers Over 40 Have Special Federal Protections
Under the federal Older Workers Benefit Protection Act, an agreement seeking a valid waiver of age discrimination claims must satisfy specific requirements.
For workers age 40 and older, these generally include:
- At least 21 days to consider an individual separation agreement containing an age-claim waiver.
- At least 45 days for certain group termination or exit incentive programs.
- Seven days after signing to revoke the age-claim waiver.
- Written advice to consult an attorney before accepting.
These protections concern waivers of age discrimination claims, not every retirement agreement. The Equal Employment Opportunity Commission also explains that employees generally cannot be prevented from filing a discrimination charge with the agency merely because they signed a severance agreement.
Read the Financial Terms Separately
The agreement should clearly explain what happens to unused vacation pay, bonuses, stock awards, health insurance, and any severance payments. Ask whether the amounts are guaranteed, conditional, paid immediately, or spread over several months.
Also check whether leaving under a voluntary retirement program changes benefits compared with an involuntary layoff. The difference may affect your overall financial position, even when the offered payment looks generous.
Before signing: Request a complete copy, ask for written answers to unclear terms, and consider an independent employment attorney. Do not assume a friendly conversation with human resources changes the written contract.
2. The Pension Election Form That Could Leave Your Spouse Without Income
For workers fortunate enough to have a traditional pension, the payout election may be one of the largest financial decisions they make before retirement.
Many pension plans offer different ways to receive benefits. One option may provide a higher monthly payment during the retiree’s lifetime, while another provides a smaller payment that continues partly or fully to a surviving spouse.
The difference may not seem significant when both spouses are healthy. However, the consequences can become serious when one spouse dies and the household suddenly loses a major source of monthly income.
A Higher Monthly Check Is Not Always the Better Deal
Consider an entirely hypothetical pension offering the following choices. The amounts are illustrations, not actual plan quotes.
| Pension Option | Monthly Income While Retiree Lives | Payment to Surviving Spouse |
|---|---|---|
| Single-life pension | $2,600 | Usually stops at retiree’s death |
| 50% joint-and-survivor | $2,450 | $1,225 monthly |
| 100% joint-and-survivor | $2,250 | $2,250 monthly |
The single-life payment gives the retiree more money each month. However, if that income disappears after death, the surviving spouse may face a much tighter budget.
The joint-and-survivor options reduce the retiree’s initial payment in exchange for continued survivor protection. Actual pension amounts depend on the plan, ages, available options, and other factors.
Federal rules require certain qualified pension plans to provide a qualified joint-and-survivor annuity to married participants unless the required written consent is obtained for another payment form. A spouse’s consent generally must be witnessed by a plan representative or notary.
Three Questions Can Change the Decision
First, determine whether your spouse could comfortably live on the remaining Social Security benefits, personal savings, and other income if your pension stopped. A household that can manage two incomes today may struggle when only one remains.
Second, ask whether the pension includes inflation adjustments, death benefits, or a guaranteed payment period. These details can change the value of different payout choices.
Third, find out when the election becomes final. Some plans allow changes before payments start but restrict changes afterward, making it important to review every option before the first payment.
Before signing: Ask the pension administrator for a written comparison of every available payout option, including what happens if either spouse dies first. Review those figures as a household rather than treating the highest monthly payment as the automatic winner.
3. The 401(k) or IRA Rollover Form That Can Create an Unexpected Tax Bill
Leaving a job often raises an important question: What should happen to the money in your employer-sponsored retirement plan?
Depending on the plan, you may be able to leave the funds where they are, transfer them into an IRA, move them to another employer plan, or withdraw the money.
These choices do not all have the same tax consequences. A rollover form that uses unfamiliar language can lead to withholding, taxable distributions, or missed deadlines.
Direct and Indirect Rollovers Are Not the Same
A direct rollover sends eligible retirement funds to the receiving retirement account without the money being paid to you. This generally avoids the mandatory federal withholding that applies when an eligible taxable distribution from an employer retirement plan is paid to you.
An indirect rollover involves receiving the money yourself and then redepositing it into an eligible retirement account. The IRS generally provides 60 days to complete that rollover, subject to specific rules and exceptions.
Consider this example involving a fully taxable, eligible $100,000 distribution from a traditional 401(k).
| Rollover Detail | Direct Rollover | Distribution Paid to You |
|---|---|---|
| Starting balance | $100,000 | $100,000 |
| Mandatory federal withholding | $0 | $20,000 |
| Amount initially received personally | $0 | $80,000 |
| Amount moved directly to receiving retirement account | $100,000 | $0 |
| Additional money needed to roll over the full $100,000 after receiving $80,000 | $0 | $20,000 |
With the indirect route, the withheld $20,000 is not automatically lost. However, you would need to replace it from another source within the applicable rollover deadline to complete a full $100,000 rollover.
If only $80,000 is rolled over, the remaining $20,000 generally becomes taxable income, with the withholding credited toward the tax owed. An additional early-distribution tax could also apply in some circumstances.
Do Not Confuse a Rollover With a Roth Conversion
Moving pretax retirement money into a traditional IRA generally allows taxes to remain deferred when the rollover qualifies. Moving pretax retirement money into a Roth IRA, however, generally creates taxable income in the year of conversion.
That distinction matters because a large Roth conversion could increase taxable income significantly. It may also affect other financial calculations, including future Medicare premiums based on income.
The IRS also identifies certain distributions, including required minimum distributions, that cannot be rolled over. Signing paperwork without identifying these amounts can lead to avoidable tax complications.
Before signing: Confirm the receiving account’s type, the exact account details, whether the transaction is a direct rollover, and how any pretax and Roth balances will be treated.
4. The Annuity Contract That Could Restrict Access to Your Own Savings
Annuities are sometimes presented to people approaching retirement as a way to receive dependable future income. Certain annuities can provide valuable guarantees, especially for retirees concerned about outliving their savings.
However, annuity contracts vary widely, and not every guarantee works the way a buyer might initially imagine.
An annuity may contain surrender charges, withdrawal limits, fees for optional benefits, complicated interest-crediting formulas, and restrictions on accessing the money early. The important terms can be spread across many pages.
The Word Guaranteed Needs a Second Look
A guaranteed income benefit does not always mean the entire account balance is guaranteed against every possible loss. Likewise, an illustrated growth rate may not represent the actual return credited to your money.
For indexed annuities, participation rates, caps, and other contract features can limit credited gains. The Securities and Exchange Commission warns that surrender charges and other contract terms can also reduce the value available when money is withdrawn.
| Contract Term | What It Means | Question to Ask |
|---|---|---|
| Surrender period | Time during which certain withdrawals face charges | How long is my money restricted? |
| Surrender charge | Fee for withdrawing above permitted amounts | What would leaving early cost? |
| Income rider | Optional feature providing certain income guarantees | What does the rider cost? |
| Participation rate | Percentage of an index gain credited under a formula | How much of an increase do I receive? |
| Rate cap | Maximum credited return under certain terms | Can the insurer change the cap? |
| Free-look period | Limited cancellation window under applicable terms | When does it end, and what refund applies? |
A Free-Look Period Is Not a Substitute for Reading
Many variable annuity contracts provide a limited free-look period, often around 10 to 30 days, although rules vary by state and product. During that period, the buyer can generally cancel without a surrender charge, but the refund may depend on the terms and investment performance.
Once that period ends, withdrawing a large amount could become expensive. Some indexed annuity surrender periods last six to ten years or longer, which is a significant commitment for money that may be needed during retirement.
Retirees should also consider the insurer’s financial strength because annuity guarantees depend on the issuing insurance company’s ability to meet its obligations.
Before signing: Ask for the complete contract, surrender schedule, fee disclosure, and a written explanation of the guaranteed versus nonguaranteed benefits. Compare the product with simpler retirement income options before committing a large share of your savings.
5. The Beneficiary Designation Form That Could Send Your Savings to the Wrong Person
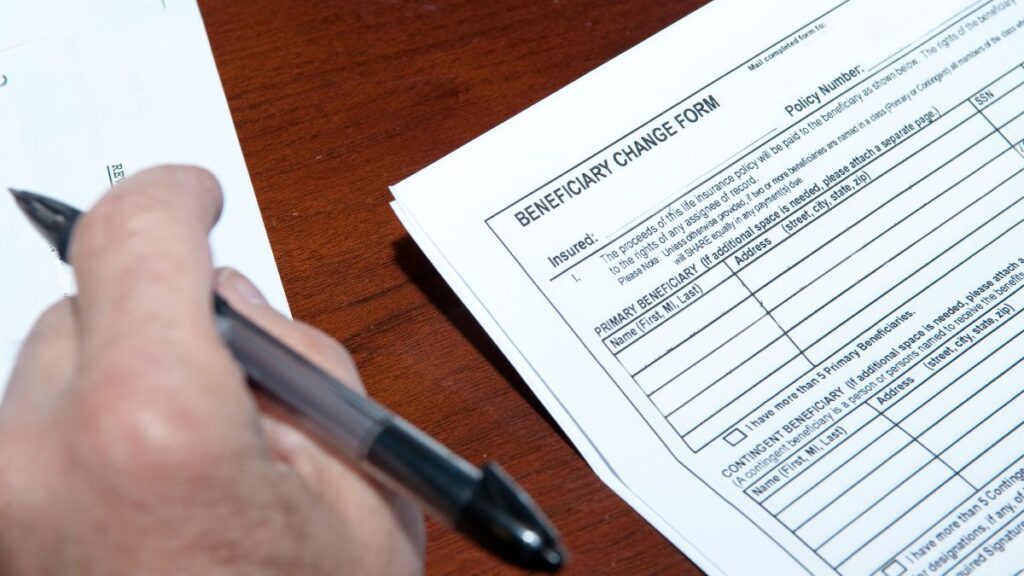
A beneficiary designation form may be only one or two pages long. Yet it can determine who receives a retirement account or insurance benefit after your death.
Many people complete these forms years before retiring and rarely review them again. During that time, marriages, divorces, deaths, births, and changes in family relationships can make the original choices outdated.
The danger is assuming that an updated will automatically fixes every old beneficiary designation. Retirement accounts and insurance contracts often use their own beneficiary rules, and the documents need to work together.
Your Family Circumstances May Have Changed
Imagine that someone named a spouse as beneficiary 20 years earlier and later divorced. The person might assume that the divorce automatically removed the former spouse from every retirement account.
That assumption can be unsafe because the answer depends on the account, plan documents, state and federal law, and any applicable divorce order. Some retirement benefits are also affected by qualified domestic relations orders.
The IRS advises retirement plan participants to review beneficiary designations after major family changes. It also explains that many plans require spousal consent when changing beneficiaries or certain benefit arrangements.
Review More Than the First Name on the Form
| Detail to Review | Why It Matters |
|---|---|
| Primary beneficiary | Identifies the first person or entity entitled to benefits |
| Contingent beneficiary | Provides a backup when the primary beneficiary cannot receive benefits |
| Allocation percentages | Determines each beneficiary’s share |
| Former spouse | May create conflicts with current wishes and legal obligations |
| Minor children | May require additional planning for management of inherited money |
| Trust designation | Requires careful coordination with the trust and applicable account rules |
Beneficiary designations should be checked across 401(k)s, IRAs, pensions, life insurance policies, and any other accounts that permit them. Different institutions may have different rules, so one completed form will not necessarily update another account.
Keep copies of submitted forms and obtain confirmation from the administrator or institution that the updates were accepted. This helps prevent uncertainty when family members later need to settle the estate.
Before signing: Review every name, percentage, and backup choice against your current family situation and estate plan. If your circumstances involve a divorce, blended family, trust, or special-needs beneficiary, consider an estate planning attorney.
6. The Power of Attorney That Gives Someone Control Over Your Money
A financial power of attorney allows another person, called an agent, to make certain financial or legal decisions on your behalf. It can be a useful document if illness, injury, or another condition prevents you from managing your own affairs.
A durable financial power of attorney generally remains effective even if the person granting it becomes incapacitated. However, exactly when the authority begins and what the agent can do depend on the document and applicable law.
The Consumer Financial Protection Bureau warns that these arrangements can create opportunities for financial abuse because an agent may receive substantial authority without routine oversight.
A Trusted Person Still Needs Clear Limits
Naming an adult child, relative, close friend, or professional may seem straightforward. However, trust alone does not answer every question about how the agent should manage your savings.
Some powers of attorney grant broad authority over bank accounts, investments, real estate, and tax matters. Depending on state law and the document, certain provisions may also permit gifts or changes affecting estate planning arrangements.
A well-prepared document should explain the powers granted, when they become effective, and whether particular actions are restricted. It should also identify what happens if the original agent becomes unwilling or unable to serve.
Pay Special Attention to These Provisions
- Effective date: Does the authority begin immediately or only after a defined event?
- Banking authority: Can the agent access accounts, transfer funds, or close accounts?
- Property powers: Can the agent sell, mortgage, or otherwise handle real estate?
- Gifting authority: Can the agent transfer your money or property to other people?
- Beneficiary changes: Does the agent have any authority over beneficiary designations?
- Oversight: Is the agent required to provide records or reports to another trusted person?
These details can matter more than the length of the document. A short, broadly worded agreement may grant extensive powers, while a carefully prepared document can establish clearer instructions and safeguards.
Do Not Forget Medical Decision Documents
A financial power of attorney is generally different from a health care power of attorney or advance health care directive. Someone authorized to manage your investments may not automatically have authority to make medical decisions for you.
Retirement planning is an opportunity to review both areas, especially if family members live far away or would find it difficult to handle an emergency. State-specific forms and witnessing requirements also deserve attention.
Before signing: Have an estate planning attorney explain the authority being granted and the available safeguards. Choose an agent based on judgment, reliability, and willingness to follow your instructions rather than family position alone.
Five Warning Signs That Mean You Should Stop Before Signing
A retirement document does not have to be fraudulent to be unsuitable. Sometimes the concern is simply that important information has not been explained well enough for an informed decision.
The following situations deserve additional questions before you proceed.
| Warning Sign | Why It Deserves Attention | Safer Response |
|---|---|---|
| Someone pressures you to sign immediately | You may miss restrictions or alternatives | Ask for the applicable deadline in writing |
| The explanation does not match the contract | Verbal promises may not be reflected in the terms | Request written clarification |
| Fees or penalties are hard to find | The real cost may be unclear | Ask for a complete fee schedule |
| You are told the choice cannot wait | Pressure may interfere with comparing options | Verify the actual deadline independently |
| You cannot obtain a completed copy | You may be unable to confirm what was agreed | Request copies and confirmation of acceptance |
One particularly useful rule is to avoid signing while important questions remain unanswered. Even when a decision has a legitimate deadline, understanding that deadline is better than relying on pressure from someone encouraging a quick signature.
A second opinion can be valuable when the document affects a large amount of money, your spouse’s future income, or legal authority over your property. Depending on the issue, that may mean consulting an attorney, tax professional, pension specialist, or financial adviser.
